Bad News, Higher Lows
Every Monday, we deliver a concise yet comprehensive briefing to help you navigate the week ahead.
Our weekly market dashboard brings together key insights across Macro, Crypto, and Onchain activity, distilled into a clear, actionable format. Whether you’re managing risk or spotting opportunity, start the week informed and aligned.
Headline
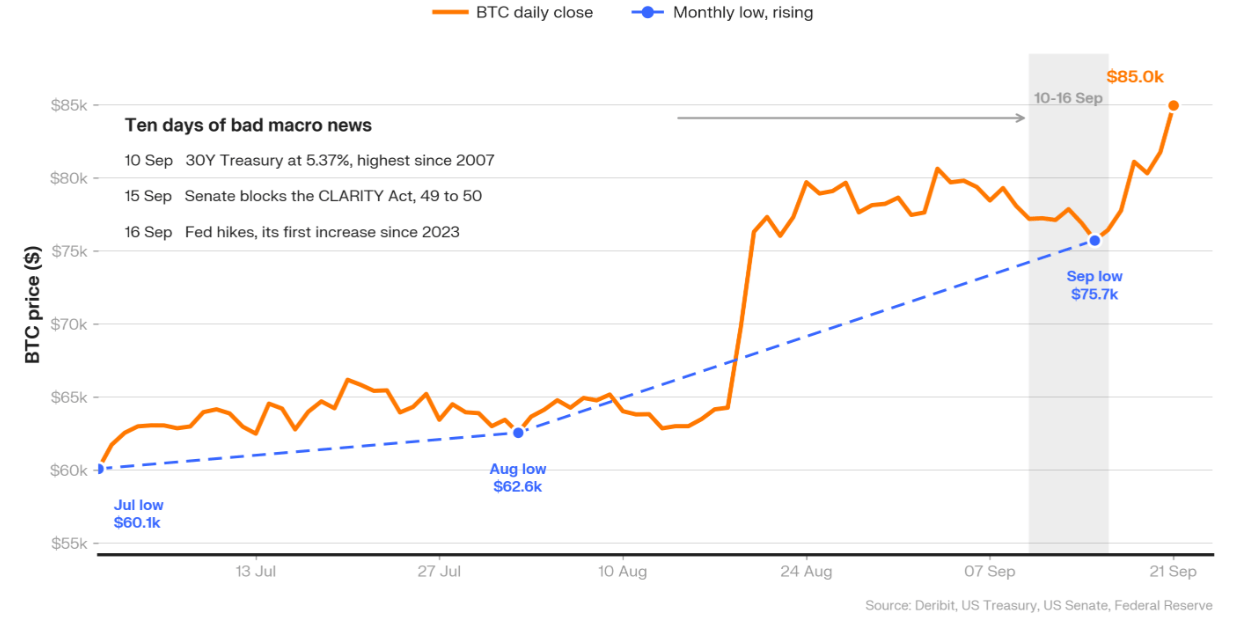
Bitcoin took the week’s worst macro news on the chin and closed at its highest weekly level of this entire run. The market continues to treat bad macro as a level to buy.
Proof
Bitcoin took the hit on Wednesday, printing $75,590 as the Fed hiked, then recovered all of it and more to close the week at $81,236, its highest weekly close of the run, and it has pushed on to $85,000 today.
Equities recovered too but far more selectively, the Nasdaq 100 up 1.8% against a Dow down 0.94% and a Russell 2000 down 1.25%. Gold made its low of $4,261.80 in the hours after the decision and its high of $4,400.60 on Friday, finishing the week higher even as the dollar gained 0.81%.
Behind all of it crude fell from almost $109 on Tuesday to $103.87 on Friday, and the ten year yield came back to 4.94% after printing 5.04%, its first move above 5% since 2007.
So What?
We have been calling this the early part of a Bitcoin uptrend for several weeks and last week is the cleanest evidence yet.
Look at what it has been handed since July. The Strait of Hormuz effectively closed, Brent above $100, the thirty year Treasury at its highest level since 2007, the ten year through 5% for the first time since 2007, the Fed’s first hike in three years with 16 of its 18 officials wanting another, and a Senate setback for the CLARITY Act.
Any one of those was a reason to sell. Instead the monthly lows keep rising, from $58,566 in July to $62,773 in August to $75,590 in September, and that September low was printed on the afternoon of the hike itself. Bitcoin also closed last week back above its fifty week moving average for the first time in forty five weeks, a level that shows has been followed by no new low in eleven of the thirteen times it has been reclaimed since 2011.
An asset that rises only on good news is a trade, while one that grinds higher as the news stays bad is being repriced, and we think this is the second thing. It matters that Bitcoin is still 33% below its October 2025 peak, because that is not the shape of a move that is finishing.
We would keep treating macro driven weakness as the market handing us a level.
Rented Rally
Headline
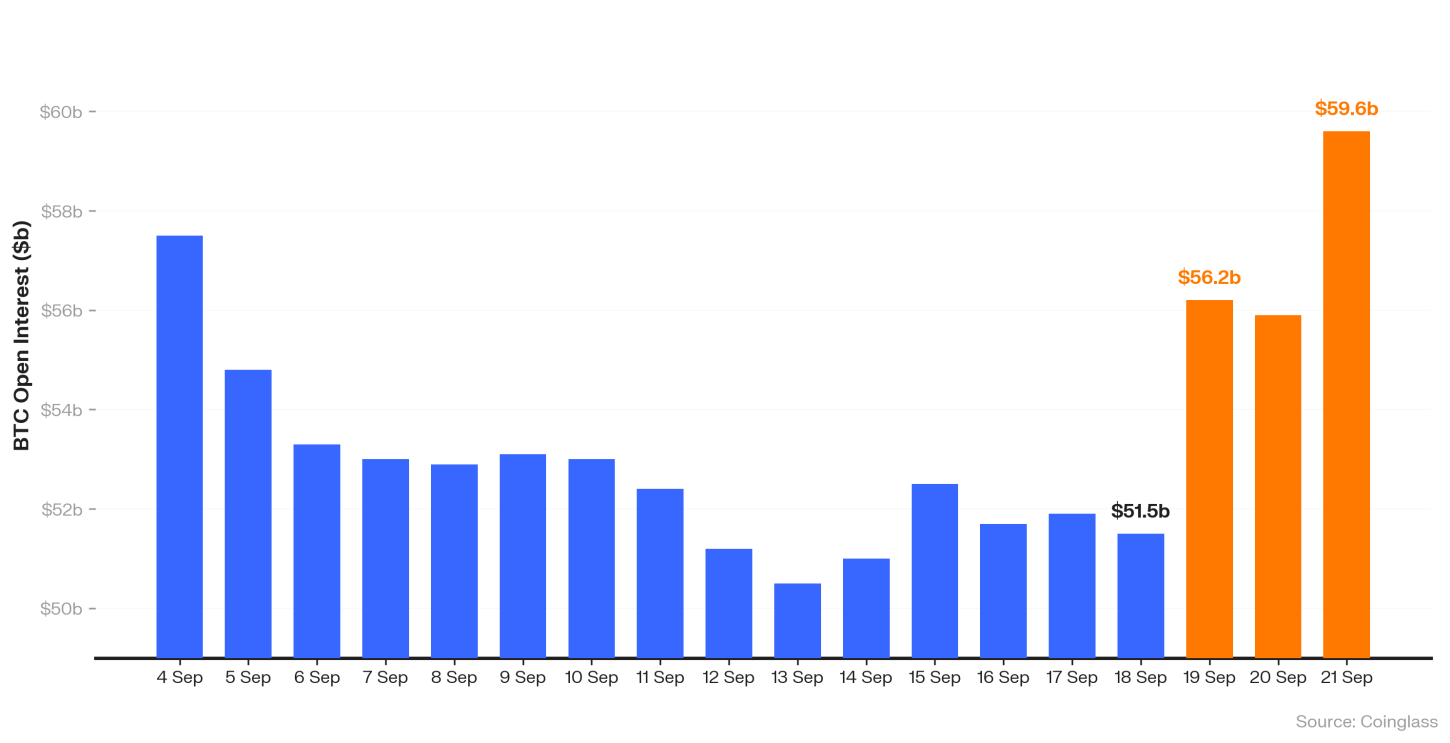
Bitcoin and Ether open interest sat flat for four sessions then ripped roughly 9% higher into the weekend, OI-weighted funding pushed to a weekly high, and the cash bid barely turned up.
Spot Bitcoin ETFs took just +$6.2m on the week and Ether ETFs shed $140m, ending a four-week inflow streak.
Proof
BTC open interest held near $51-52b Monday through Thursday, then jumped to roughly $56b by Saturday 20 Sep, a WoW gain of about 9%, and pushed on to $59.6b by the 21st.
ETH OI traced the same shape, from about $31b to $34.6b. Funding climbed the whole way, BTC OI-weighted funding rose steadily, while ETH funding dipped briefly negative on 15 Sep before recovering, with holders choosing to earn on the long side rather than sell. The ETF tape ran the other way.
Bitcoin funds netted +$6.2m across the five sessions, essentially flat, the week’s biggest outflow of -$450.3m on Tuesday 15 Sep offset by +$433.0m on Friday 18 Sep. Ether funds ran -$140m, Solana funds took +$60.7m, and XRP funds +$9.6m.
Underneath the majors, capital rotated hard down the risk curve. Our L2 proxy basket ran +41%, DeFi +19%, RWA +18%, AI +16% and memecoins +13%, while large cap L1s lagged at +10%.
So What?
This move is renting leverage, not buying spot. When OI and funding lead while ETF creations sit near zero, the marginal buyer is a levered long on a perp rather than an allocator in a fund wrapper, and that is a thinner, more reflexive bid. The same funding that is fuelling the move becomes the accelerant for a long squeeze the moment spot stalls.
We want the ETF bid to reconnect with the derivatives bid next week. If Bitcoin ETF creations stay below $50m a day while BTC OI holds above $56b, the path of least resistance is a funding reset lower, not a continuation.
The cleaner signal is the Solana ETF tape, Friday’s +$47.6m BSOL print is the ‘rotation down the cap curve’ trade in miniature, and a second week of it confirms institutions are working the newer altcoin wrappers while they leave the majors alone.
Three things to watch into next week include Bitcoin ETF daily creations against the $50m line, the $56b BTC OI level, and the next Solana ETF weekly print.
Liquidity’s New Home
Headline
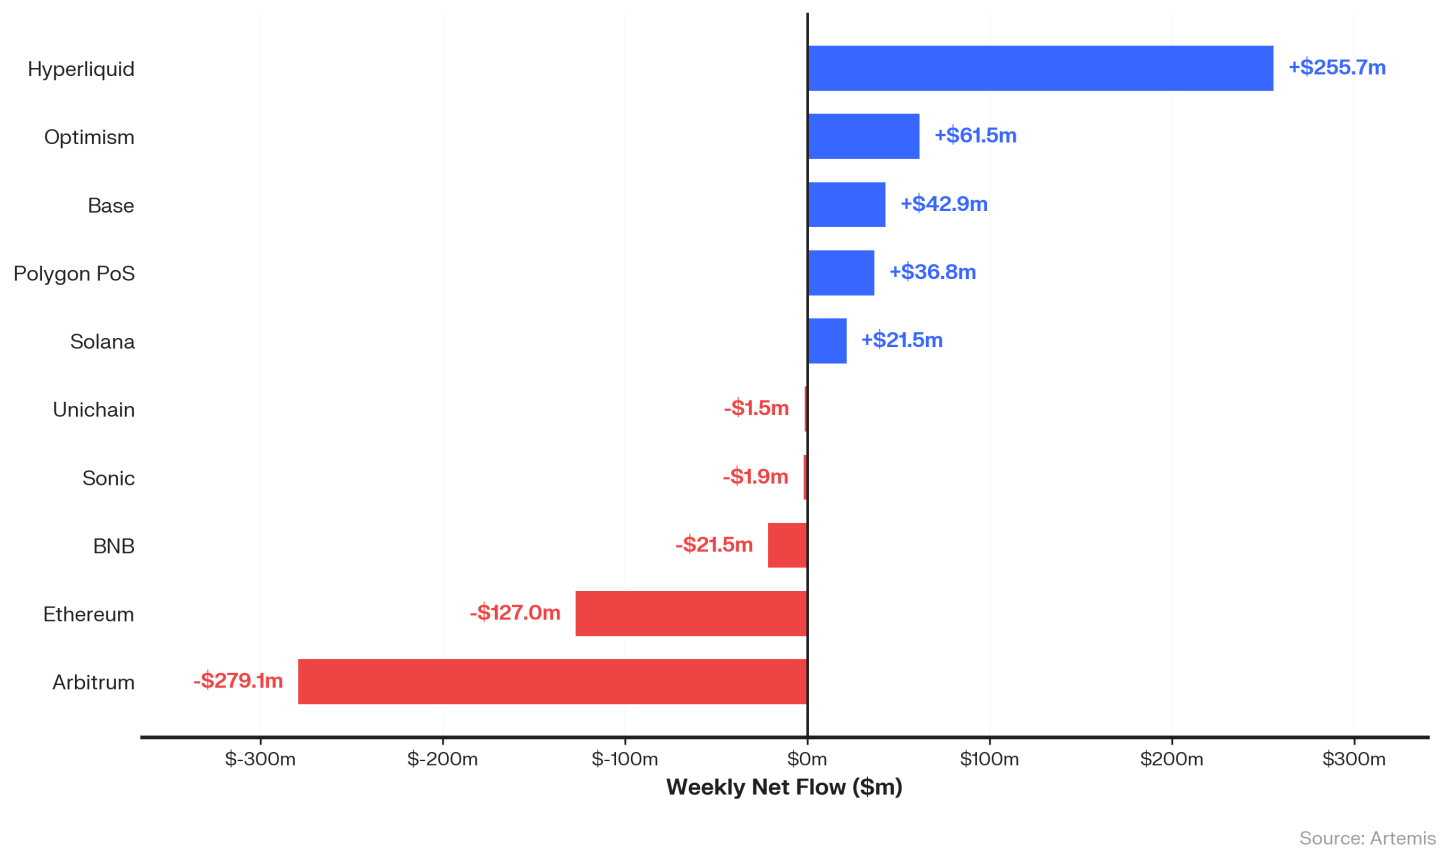
Hyperliquid launched native borrow and lend on 18 Sep and pulled a net +$255.7m inflow, the largest of any chain, while Arbitrum bled -$279.1m and Ethereum -$127m. The stablecoins that funded it came out of Aave, where USDT supply fell 8.43% and the rate jumped to 3.70%.
Proof
Hyperliquid’s +$255.7m dwarfed every other chain (Optimism +$61.5m, Base +$42.9m, Polygon +$36.8m, Solana +$21.5m), while Arbitrum’s -$279.1m was the biggest outflow ahead of Ethereum -$127m and BNB -$21.5m.
The inflow came from a product launch with Hyperliquid opening native manual borrow and lend on 18 Sep, $269m borrowed on day one against $400m of supplied liquidity, HYPE printed an all-time high of $92.56, and perp open interest hit a record $8.1b on 20 Sep, around 11% of the global total.
Hyperliquid deposits bridge through Arbitrum’s USDC contract, so that inflow shows up as Arbitrum’s outflow and the two nearly net out, even as ARB the token ran +63% on unrelated Robinhood Chain volume. Aave shows the same rotation. USDT supply fell 8.43%, from $3.178b to $2.91b, and its rate rose 16.35% to 3.70%, a thinning pool repricing upward as depositors left. Against that, WETH deposits rose 6.90% to $5.733b as its rate fell to 1.44%, and WBTC deposits rose 10.10% with its rate pinned at 0.01%, holders parking ETH and BTC as collateral to earn yield rather than borrow against it.
RWA ran a narrative versus fundamentals split, where ONDO, CFG and PENDLE ripped 18-33% on the SEC’s 17 Sep tokenised stock exemption, yet aggregate onchain RWA AUM fell 1.75%, dragged by Centrifuge -18.85% on a single Grove-backed Janus Henderson CLO redemption, with Securitize -6.37% and Maple -6.27% on routine flow.
So What?
On perps, leverage built all week, onchain, the money did the opposite. ETH and BTC holders parked collateral for yield and stablecoins chased a brand new lending venue rather than levering up.
The marginal onchain dollar went to where the yield is newest, Hyperliquid, and that is the venue to watch. While its fresh lending book out pays Aave’s 3.6% USDC, the stablecoin drain from Aave and Arbitrum continues, and that record $8.1b open interest becomes a concentration risk the moment HYPE turns.
Three things to watch into next week, whether Aave USDT supply stabilises or keeps falling from $2.91b, whether Hyperliquid’s borrow book holds above its $269m day one level, and whether RWA AUM prints a second down week after -1.75%, because the token prices are discounting a 2031 regulatory option, not this quarter’s flows.
Solana’s Stock Room
Headline
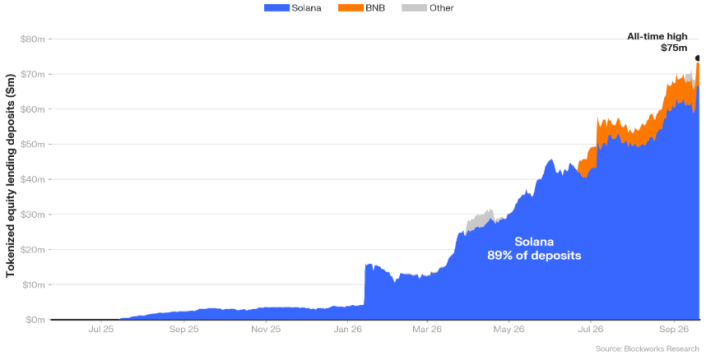
Tokenized equity lending hit an all-time high last week, and nearly nine in ten of those dollars sit on Solana.
Proof
The value of tokenized stocks posted as collateral in onchain lending climbed to a record $74.5m over the weekend, up more than 1,800% from under $4m at the start of the year.
Solana holds 89% of that total and BNB is the only other chain that registers, at 10%. The record landed in a busy week for the theme.
The SEC granted five year relief for onchain trading of fully backed stock tokens on Thursday, two days after the Senate blocked the CLARITY Act, and Tether and Circle together minted $750m of stablecoins on Solana in a single session.
So What?
We think Solana is quietly becoming the home for tokenized real world assets while Washington is still arguing about the rulebook.
The absolute numbers are small, $74m of lending collateral against a tokenized stock market worth a few billion, so this is an early read rather than a mature one, but the direction has been one way for a year and the concentration is hard to ignore, especially as stablecoin issuance keeps flowing to the same chain.
We would watch whether the SEC’s new trading exemption pulls this activity onto regulated US venues over time, or whether Solana’s head start in stock tokens compounds from here. For now the collateral is voting for Solana.